Cross-border workers in Luxembourg
How many remote working days do you have left?
Cross-border workers may spend a limited number of days working outside Luxembourg without changing how they are taxed. Cross that line and it is not just the extra day that becomes taxable at home — it is every day worked outside Luxembourg, from the first. This counter shows you where you stand.
Nothing is sent: the calculation runs in your browser and your days stay on your device.
Log my days in the calendar → All app features →
Only if your contract starts or ends during the year. The threshold is reduced pro rata to the period of employment for France (and, to be safe, Belgium), not for Germany. Days before the start and after the end do not count.
For Germany, the 34 days are not reduced – neither for part-time work nor when starting or leaving during the year (mutual agreement of 11 Jan 2024, BMF letter of 15 Jan 2024).
Remote work, business travel and training outside the Grand Duchy, since 1 January.
Basis for the social security threshold. Around 230 days for full time. With a contract start or end during the year, it is reduced pro rata automatically.
34
Every day counts on its own. One hour started outside Luxembourg uses up a full day (for Germany: from 30 minutes).
Below 25 % remote work you stay covered by the Luxembourg CCSS automatically; up to this mark (49.9 %) only if your employer applies for it (framework agreement, A1 certificate). This threshold is entirely separate from the tax one.
My counter
Log your days outside Luxembourg
Tap a day to log it. The counter stays on your device — no account, nothing is sent.
New: the app
Counting without thinking about it.
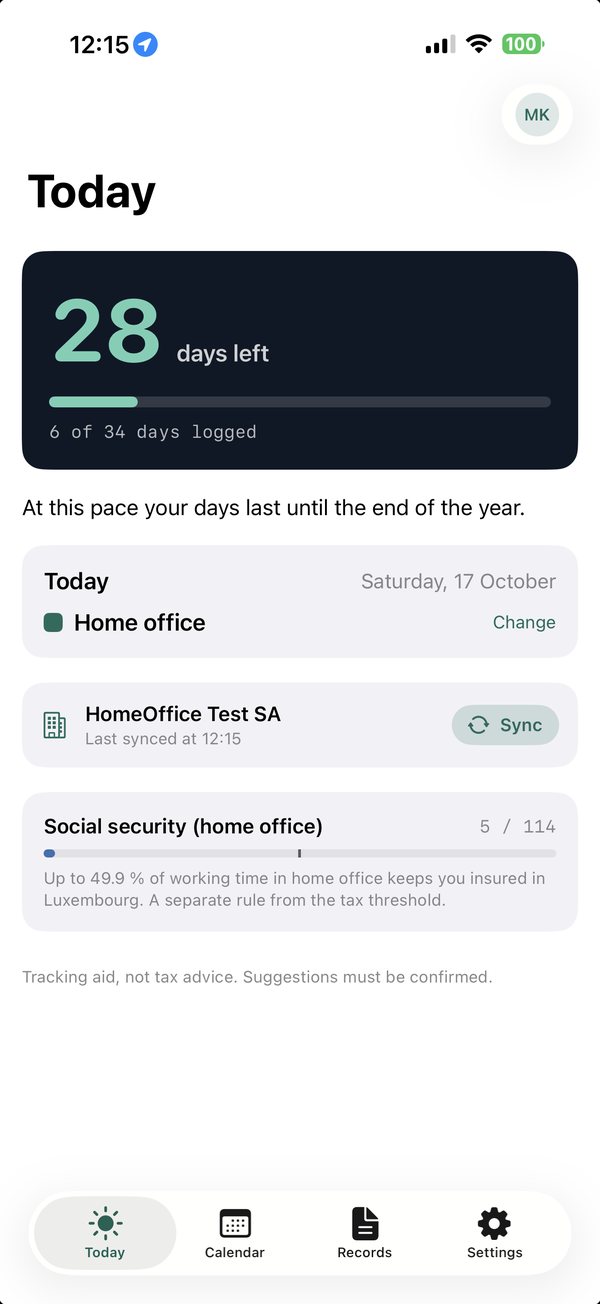
The free app for iPhone and Android asks you one question in the evening, counts your days outside Luxembourg and creates the annual statement as a PDF.
- 1Set upChoose your country of residence, contract hours and working days per year. If you have already logged days in “Mon compteur” on this website, the app imports them on first launch.
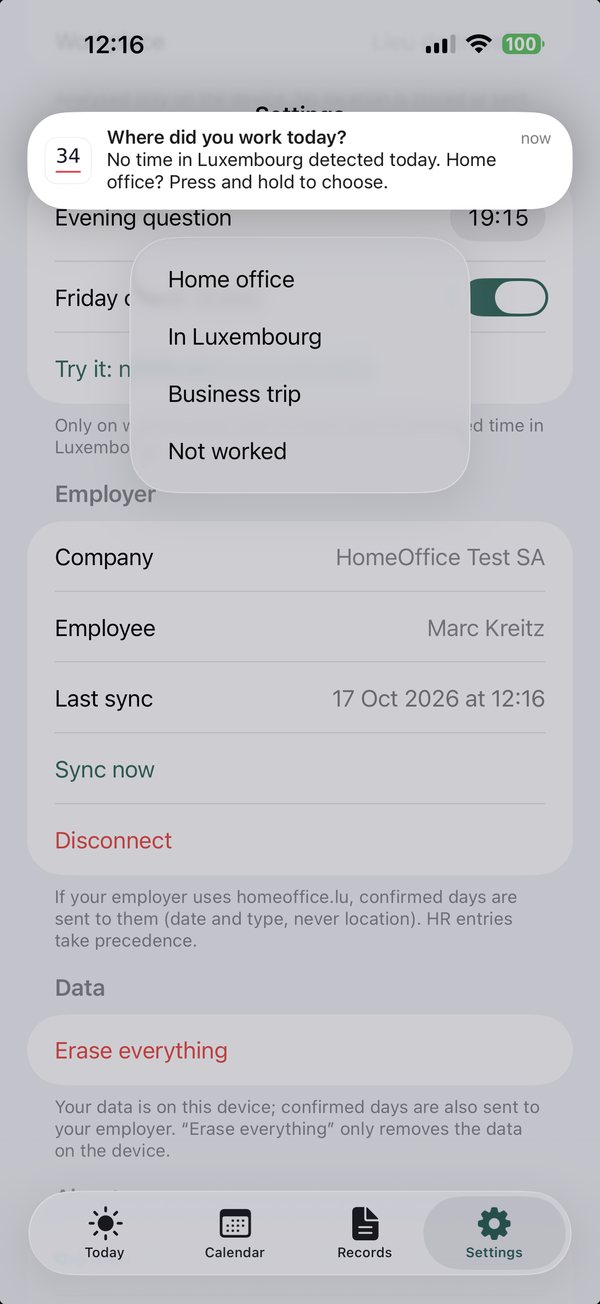
- 2Answer in the eveningOn working days without an entry, the app asks at 7 pm: where did you work today? Press and hold, tap, done.
- 3Keep recordsUnder “Records” you can create the annual statement as a PDF at any time, with your name and signature.
You’re not alone
The numbers behind your threshold
cross-border workers are employed in Luxembourg — each with their own 34-day threshold. You too.
Cross-border workers by country of residence, 2025
Day 35 changes everything
1 day too many is enough: every working day outside Luxembourg then becomes taxable in the country of residence.
Sources: STATEC, figures of 12 October 2026 · Luxemburger Wort, October 2026 · Chambre des Députés, file 8121.
Day 35 in practice
How much of your salary flips on day 35?
Beyond 34 days it is not just the extra days: every day worked outside Luxembourg becomes taxable in the country of residence, from the very first. The salary is then split pro rata to the days worked in each country.
Home office, business trips and training outside Luxembourg count; a day started counts as a full day (Germany: from 30 minutes). The amount of tax depends on the rates in the country of residence and the household situation; Luxembourg tax falls accordingly. General information, not tax advice.
Sources: Frontaliers Grand Est — France · Belgique · Deutschland
Simulation
When will you hit the threshold?
Pick a home-office rhythm or click individual days. Calculated on Luxembourg working days in 2027, public holidays excluded.
Simplified full-time simulation, without leave or business trips. For your exact situation, use the calculator at the top of the page.
Don’t get caught out: we remind you before it gets tight.
Get an alert →Employers & public bodies
Running a company or public body with cross-border staff?
With homeoffice.lu for employers and public bodies, your HR team sees every employee’s count at a glance — tax threshold, social security and your internal remote-work rule, with alerts, personal links and annual statements.
Three things that catch almost everyone out
Half an hour is a whole day
What counts is physical presence. Work two hours at home in the morning, then drive to the office in Luxembourg, and a full day of your budget is gone. There is no counting by the hour or the half day. In Germany, less than 30 minutes of work does not count.
All or nothing
Exceed the threshold by a single day and it is not that one day that becomes taxable at home — it is every day you worked outside Luxembourg that year.
The proof is on you
The burden of proof sits with the taxpayer, not the employer and not the tax office. Employment contract, time records, travel tickets, hotel invoices, mission orders and attendance lists can all be requested. Keep a running record.
A worked example
Anne lives in Thionville and works full time in Kirchberg. By the end of July she had worked 18 days from home, spent 3 days at a training course in Paris and 2 days on a business trip to Brussels.
18 + 3 + 2 = 23 days used. Of her 34, eleven are left for the rest of the year.
At one remote day a week that lasts until mid-October. After that she either goes to the office or crosses the line — and every day worked outside Luxembourg becomes taxable in France, from the first, not only the ones above the threshold.
What counts and what does not
Counts towards the threshold
- Remote work from your country of residence
- Days worked in a third country for your Luxembourg employer
- Business travel outside Luxembourg
- Training attended outside the Grand Duchy
Does not count
- Holiday
- Sick days
- Weekly rest and public holidays not worked
- Force majeure beyond the control of either party
Special cases
Travel to a third country
A working day in Frankfurt or London for your Luxembourg employer counts towards the 34 days exactly like a day at your kitchen table. What matters is not where you live but that you worked outside the Grand Duchy.
Starting mid-year
If you start during the year and live in France (or, to be safe, Belgium), the threshold is reduced pro rata. Start in July and it is around 17 days, not 34. The same reduction applies to part-time contracts, and it is always rounded down. In Germany it stays at 34 days.
There is no half day
One hour of work at home before you set off? A full day. Counting is based on physical presence, not on hours worked. Regularly starting at home in the morning burns through the budget far faster than people expect. In Germany, less than 30 minutes does not count.
Two independent systems
Tax and social security follow separate rules. You can be entirely within the social security limit and still be far over the tax threshold. The reverse is rare but possible.
What happens if you go over?
First, to be clear: this is not an offence. Working more than 34 days outside Luxembourg is allowed — it only changes who gets to tax your salary.
- The share of your salary matching every day worked outside Luxembourg becomes taxable in your country of residence.
- You will need a tax return at home, and your employer will usually have to split your pay between the two countries.
- Is it more expensive? That depends on the rate. In some situations it is actually cheaper. There is no general answer — it needs a calculation for your own case.
- Keep your records. Since the burden of proof is on you, your documentation is what decides which number stands if you are audited.
The other way round: Luxembourg resident working from abroad
The 34-day threshold only applies to cross-border workers. Someone living and working in Luxembourg falls outside it entirely — and still asks the same question: what happens if I work two weeks from Italy, Portugal or Spain? That runs on a different set of rules.
Rarely a tax problem
As a Luxembourg tax resident you are taxed in Luxembourg on your worldwide income. The other country normally only steps in beyond 183 days of presence in the year, or if your employer has a permanent establishment there or bears the salary cost. Two weeks of working by the sea therefore changes nothing as a rule.
The A1 certificate is almost always missing
The moment you work in another EU country for your Luxembourg employer, you need an A1 certificate from the CCSS — in principle from day one. It proves you remain covered in Luxembourg. Without it you are formally uncovered in an inspection, and several countries now actively check remote work.
The EU framework agreement does not help here
The 49.9 % limit only covers telework carried out from your country of residence. If you live in Luxembourg and work from Italy, Italy is a third country: legally this is a posting, not remote work, and different rules apply.
The bigger risk sits with the employer
When employees work from abroad for longer periods and possibly develop business there, a permanent establishment can arise — bringing corporate tax liability in that country. Many companies therefore set firm caps on working from abroad. Ask HR before you book.
Keep a record
Since the burden of proof is on you, a dated record beats a memory. Print your position or email it to yourself.
For printing, nothing leaves your browser. For email, the figures, name and employer are sent once to our server, laid out as a PDF and dispatched — none of it is stored, not even the email address.
Get an alert
We write to you when a rule changes (34-day threshold, social security, home office) and, at the start of each month, send a short reminder with your personal threshold. No advertising, one-click unsubscribe.
We store your address, your language, your country of residence and your working time. Nothing is shared with third parties. One-click unsubscribe in every email.
Common questions
How many remote working days are allowed?
For cross-border workers resident in France, Belgium and Germany the tolerance threshold is a uniform 34 days per year outside Luxembourg. Below that, the entire salary stays taxable in Luxembourg.
What happens if I go over?
The right to tax every day worked outside Luxembourg moves to your country of residence, not just the days above the threshold. That can mean a tax return at home and a split of your salary between two countries.
What does social security have to do with it?
Nothing — and that is the most common misunderstanding. For social security you stay with the Luxembourg CCSS below 25 % home office, and up to 49.9 % (roughly 114 days depending on your contract) if your employer applies for it (framework agreement, A1 certificate). The 34-day tax threshold sits far below that and applies independently.
Could the number 34 change?
Possibly. France and Luxembourg are discussing an increase, so far without agreement; there are no negotiations with Belgium or Germany. Until something is ratified, the current rule applies. We update this page as soon as anything changes.
Who should keep count?
Anyone regularly working outside Luxembourg for a Luxembourg employer. Since the burden of proof falls on the employee, a record kept through the year is far safer than a reconstruction in December.
I live in Luxembourg — does the 34-day threshold apply to me?
No. It only concerns cross-border workers resident in France, Belgium or Germany. A Luxembourg resident is taxed in Luxembourg anyway. If you work temporarily from another country, what you need instead is an A1 certificate from the CCSS, and beyond roughly 183 days of presence the other country may become competent for tax.
Underlying rules
The information on this page is based on the following:
- Circular of the Luxembourg director of taxation of 24 June 2026 on how the 34 days are counted
- Amendment to the Luxembourg–France tax treaty, applicable since 1 January 2023, ratified in February 2025
- Luxembourg–Belgium amending protocol of 31 August 2021 (approved by Luxembourg law of 22 June 2022), effective from 1 January 2022
- Tolerance threshold with Germany, raised from 19 to 34 days on 1 January 2024
- European framework agreement on teleworking of July 2023 (49.9 % limit for social security)
Who runs this site
homeoffice.lu is run by iSOLUTIONS S.à r.l., a company registered in Luxembourg (RCS B84137). We are not tax advisers. This site summarises publicly available rules and does the arithmetic for you — it does not replace advice on your own situation.
Found a mistake, or has a rule changed? Write to hello@homeoffice.lu.
Updated: